Family & Survivors
Finance & Family Benefits
How your rating protects your income, your dependents, and your family future
A disability rating is not just a monthly check. It unlocks dependent add-ons, family health care, education transfer, and survivor protections that can change your family financial picture for decades.
Your Rating Supports More Than You
Once you reach a 30 percent combined rating, the VA pays additional compensation for eligible dependents, a spouse, children, and in some cases dependent parents. Many veterans never file the dependency paperwork and quietly leave that money on the table for years.
The deadline matters. Under §3.401(b), if you notify the VA of a dependent within one year of the qualifying event, the marriage, the birth, the rating reaching 30%, the added compensation is effective from that event. File later and the effective date is generally the date the VA received your notice. Every month of delay is money that does not come back. The form is VA Form 21-686c.
Family Financial Protections
Dependent add-on compensation
Additional monthly amounts at 30% and above for a spouse, each child under 18, each child 18–23 in school, and dependent parents. An additional amount applies where a spouse requires aid and attendance.
Helpless child benefits
Under §3.356, a child permanently incapable of self-support before age 18 can remain a dependent for life. This is a substantial, lifelong benefit that families routinely never learn about.
CHAMPVA
Health coverage for the spouse and dependent children of a veteran rated permanently and totally disabled, or who died of a service-connected condition. Not available where the dependent is TRICARE-eligible.
Chapter 35 Dependents’ Educational Assistance
Education benefits for the spouse and each eligible child of a P&T veteran, usable for degree programs, certificates, and apprenticeships.
Post-9/11 GI Bill transfer
A separate DoD program requiring transfer while still serving. Distinct from Chapter 35, and a family can be eligible for both.
Survivor protection
A total rating held for 10 continuous years before death creates DIC eligibility for a surviving spouse under §3.22, regardless of the cause of death.
DEA or the Fry Scholarship: The Choice You Only Get to Make Once
There are two very different education benefits for a veteran's family, and they pay very differently. If your family qualifies for both, the VA makes you pick one, and that choice is permanent. Pick wrong and you can leave a lot of money on the table. So let me walk you through it before anyone signs anything.
DEA (Chapter 35) is for the spouse and children of a veteran rated permanently and totally disabled from service, or who died of a service-connected condition or while a P&T rating was in place (38 U.S.C. Chapter 35, 38 CFR 21.3021). It also reaches families of service members who are missing, captured, or hospitalized with a disability expected to be total and permanent. It pays a flat monthly amount straight to the student: $1,574.00 full time, $1,244.00 three-quarter time and $912.00 half time for the school year that started October 1, 2025.
The Fry Scholarship is for the children and surviving spouse of a service member who died in the line of duty on or after September 11, 2001. It pays at the Post-9/11 GI Bill level: tuition and fees sent to the school, a monthly housing allowance based on the school's ZIP code, and a books stipend. For a full-time student living off campus, the housing allowance alone often beats the entire DEA check before tuition is even counted.
That does not mean Fry always wins. For a low-cost online program with little or no housing allowance, DEA can come out ahead. Run the numbers for the actual school, not the brochure.
Months, Deadlines and Remarriage: The Rules That Changed
Families are still planning around rules that no longer exist. How many months: if you first use DEA on or after August 1, 2018, you get 36 months of full-time entitlement. If you started before that date, you get 45 months. Part-time study pays less and uses up less entitlement.
The deadline is gone for many families. If the qualifying event, the child turning 18, or finishing high school happened on or after August 1, 2023, there is no time limit to use DEA. The old windows, generally 10 years for a spouse and ages 18 to 26 for a child, only apply when everything happened before that date. I regularly meet spouses who were told years ago they missed their chance and never checked again. Check again. For Fry, a child who turned 18 or finished high school on or after January 1, 2013 has no expiration date.
Remarriage hits the two programs differently. A surviving spouse generally loses DEA on remarriage, unless the same age-57 exception in 38 U.S.C. 103(d)(2)(B) applies, and a spouse who remarries does not take DEA away from the children. Under current law, a surviving spouse keeps the Fry Scholarship after remarrying and can keep drawing DIC while using it.
The DIC Collision, and How to Apply Without a Mistake
Here is the one nobody warns families about. A child 18 or older who receives DIC in their own right because they are in school cannot be paid that DIC and DEA or Fry at the same time (38 U.S.C. 3562). An 18-to-23-year-old student has to choose: the monthly DIC, or the education benefit. Put both numbers side by side first. This bar does not apply to a surviving spouse using Fry.
To apply for DEA or Fry, file VA Form 22-5490. Online at VA.gov is the fastest. If the student has already started a program, the school's certifying official sends VA Form 22-1999 to certify enrollment, and payment does not start until that certification reaches the VA.
One more thing for families with someone still in uniform. Transferring unused Post-9/11 GI Bill months to a spouse or child is a Defense Department program, and the transfer has to be requested while the service member is still serving, with an added service commitment. Once they are out, that door is closed.
Your part: before you file the 22-5490, get the real tuition, fees and housing allowance for the specific school, and bring me the DIC award letter if a child is receiving DIC. We will lay out every option side by side so your family makes the one-time choice with the numbers in front of you, not a guess.
Family SGLI: Insuring Your Spouse and Children While You Serve
Life insurance is the benefit families only think about on the worst day of their lives, and by then the window to fix a gap is usually closed. While the service member is covered by full-time SGLI, Family Servicemembers' Group Life Insurance (FSGLI) can insure a spouse for up to $100,000, in $10,000 steps, but never more than the member's own SGLI amount (38 U.S.C. 1967).
The premium is set by the spouse's age, not health. There is no medical exam and no health questionnaire. Per $10,000 of coverage, per month: Under 35: $0.40, 35-39: $0.47, 40-44: $0.62, 45-49: $0.85, 50-54: $1.35, 55-59: $2.30, 60 and older: $4.00. Run the math before you assume it is expensive. A 42-year-old spouse carrying the full $100,000 pays $6.20 a month.
Every dependent child is insured for $10,000 at no cost. No premium, no application, and it cannot be declined. Because it is automatic, families forget it exists. If a dependent child dies while the member is serving, file the claim.
Here is the trap. A civilian spouse is generally enrolled automatically once the marriage is in DEERS. A spouse who is also in the military is not. Military-to-military couples have to elect spouse coverage in the SGLI Online Enrollment System (SOES) on milConnect. Families find this out after a death.
The 120-Day Window to Keep Your Spouse Insured
When FSGLI ends, the spouse gets 120 days to convert it to a permanent individual policy with a participating commercial insurer, and no proof of good health is required. That is the whole value. A spouse with diabetes, a cancer history or a heart event can lock in coverage a private underwriter would turn down or price out of reach.
The clock starts on separation from service, divorce, the member's death, or the member canceling spouse or own coverage. Coverage itself ends on the 121st day. Miss the window and it is gone.
Your part: check the FSGLI line on the LES once a year and after every marriage, divorce, birth or change in your own SGLI amount, because the system does not check itself. The day separation orders or a divorce decree are signed, put day 120 on the calendar.
VGLI: The 240-Day Window You Cannot Get Back
The SGLI you carried in uniform does not follow you home. It ends a short time after you separate, and nobody calls to remind you. Veterans' Group Life Insurance (VGLI) lets you convert it into renewable term coverage you can keep for life, up to $500,000 in $10,000 steps, but never more than the SGLI you had when you got out (38 U.S.C. 1977).
Here is the part that matters most. Apply within 240 days of separation and you do not have to prove good health. Your medical record cannot be used to turn you down. After day 240 you can still apply up to 1 year and 120 days from separation, but now you answer health questions and you can be denied. After that final date, VGLI is gone for good.
I see the same mistake over and over. A veteran with a bad back, a heart history and a PTSD diagnosis decides to shop around first. By the time a private insurer says no, the 240 days are over. For a veteran whose health is complicated, VGLI inside the window may be the only real coverage on the table.
If you start below the maximum, you can add $25,000 one year after VGLI begins and every 5 years after that, with no health questions, up to $500,000, but only until age 60. Apply online through the Office of Servicemembers' Group Life Insurance or on SGLV 8714, and send the first premium with it.
Your part: the day you get your DD-214, count 240 days forward and write that date on the calendar in ink. Apply before it, even if you plan to keep shopping. You can always drop VGLI later. You cannot get the no-health-questions window back.
The Premium Climbs Every Five Years, So Plan for It
VGLI is not cheap, and the cost steps up every time you move into a new 5-year age band. Using VA's current rate table, $250,000 of coverage costs $47.50 a month at age 48, $125.00 at age 58, and $345.00 at age 68. Same policy, same face amount. Only your age changed.
That is why many veterans lower their VGLI amount as they get older instead of dropping it. Cutting coverage keeps a policy you cannot replace. Dropping it ends it.
Now compare VALife. If you have any service-connected rating, even 0%, and you are 80 or younger, you can get up to $40,000 of whole life coverage with no health questions, and the premium is locked at your age when you apply. $40,000 costs $160.40 a month if you start at 55 and $200.00 if you start at 60. The catch: full coverage starts 2 years after you apply. If you die in those 2 years, your beneficiaries get the premiums back with interest, not the face amount.
Here is how I think about it. VGLI buys a bigger number for your family now, at a price that keeps rising. VALife buys a smaller, permanent number at a price that never moves. A healthy veteran may find a private term policy cheaper than either. The right answer depends on your health, your age and what your family would actually need, and it is often a combination.
Your part: before you decide, write down three numbers: what your family would need if you died this year, what you can pay each month without strain, and your service-connected rating. Bring them to me and we will lay VGLI, VALife and a private quote side by side.
VMLI: Keeping the Adapted Home If the Worst Happens
If you received a Specially Adapted Housing (SAH) grant, there is a companion benefit most families never hear about. Veterans' Mortgage Life Insurance (VMLI) pays up to $200,000 of your remaining mortgage directly to the lender when you die, so your spouse is not forced to sell the home you adapted (38 U.S.C. 2106).
To qualify you need a severe service-connected disability, the SAH grant, title to the home and a mortgage on it, and you must apply before your 70th birthday. There is no medical exam. After 70, the door is closed.
Understand what it is and what it is not. VMLI is decreasing term: the coverage equals what you still owe, capped at $200,000, so it shrinks as you pay the loan down. It is not cash to your family. It has no cash value, and it ends when the loan is paid off or the home is sold.
Here is the trap. The VMLI paperwork comes with the SAH grant, gets set on the counter with the contractor bids, and never goes back. The other trap is the refinance. If you refinance, change lenders or sell, tell the VA Insurance Center, or the policy may not pay the right lender the right balance.
Your part: if you have an SAH grant, ask your VA housing agent about VMLI and complete VA Form 29-8636 with them. If you already have it, pull your last mortgage statement once a year and confirm VA has your current lender.
When the VA Says You Owe Money Back
Sooner or later a lot of veterans open a letter that says they were overpaid, and the number on it can be thousands of dollars. Most of the time the veteran did nothing dishonest. A life change happened, the VA was not told, or was told and did not act, and the payments kept coming at the old rate. The VA counts the overpayment from the date the change should have taken effect, not the date anybody noticed.
The changes that cause it are ordinary ones. A divorce. A child who turns 18 and is not in school. A school child who drops out or graduates. A spouse or dependent parent who passes away. Each one lowers your rate, and each one is your job to report. VA Form 21-686c is not just how you add a dependent. It is also how you remove one. Others catch veterans off guard: going back on drill or active duty pay for the same days you were paid compensation, or a felony incarceration, which cuts compensation starting on the 61st day under 38 CFR §3.665.
Here is the trap. The first instinct is to put the letter in a drawer, or to just start paying. Both can cost you. The clock that matters most is 30 days. If the VA receives a written dispute or waiver request within 30 days of the debt notice, it is supposed to hold off on taking money out of your monthly benefit until it makes a first decision. Miss that, and the withholding can start while you are still figuring out what happened.
Your part: the day the letter arrives, write down the date on it. Then check it against what actually changed in your family and when. If you cannot match the debt to a real event, or the VA had your paperwork and sat on it, do not pay it and do not ignore it. Send it to me before the 30 days are gone.
Dispute, Waiver, or Payment Plan: Picking the Right Answer to a VA Debt
There is more than one way to answer a debt letter, and they are not the same request. A dispute says the debt is wrong. A waiver says the debt may be right, but collecting it would be unfair. A payment plan says you owe it and need time. Pick the wrong one and you can give up an argument you never had to give up. Under Schaper v. Derwinski, when you challenge whether the debt was properly created, the VA has to decide that question before it decides a waiver.
Your part: do not sign up for a repayment plan before you know whether the debt is valid and whether a waiver is on the table. Once you agree to pay, you are treating the debt as yours.
Family changes create most debts
A child leaving school, a divorce, or a death in the family each lowers your rate. If you reported it on time and the VA kept paying you anyway, that matters. Fault on the VA’s side is part of the waiver analysis, so keep the date you sent the paperwork and proof that you sent it.
Dispute the debt if the number is wrong
Debts get created on the wrong date, at the wrong rate, or for a dependent who was reported months earlier. Ask for the math: the period covered, the rate you were paid, and the rate the VA says you should have been paid. If the start date is wrong, the whole number is wrong, and you do not owe what you were never overpaid.
Ask for a waiver if collecting it would be unfair
Under 38 U.S.C. §5302, the VA can waive a debt when collecting it would be against equity and good conscience, and the request generally has to be filed within 180 days of the notice. Under 38 CFR §1.965 the VA weighs your fault against its own, whether repaying would cause undue hardship, whether it would defeat the purpose of the benefit, unjust enrichment, and whether you relied on the money to your detriment. A waiver is barred if there was fraud, misrepresentation, or bad faith.
Use a payment plan only when the debt is real
If the debt is valid and a waiver will not work, you can ask for a repayment plan or a smaller monthly withholding instead of losing most of your check. The VA will want your finances on VA Form 5655, Financial Status Report. Fill it out honestly and completely. A vague form gets you the standard withholding, not the one you can live with.
Plan for the Long Game
A Permanent and Total (P&T) rating is the single most valuable designation for a veteran’s family. It locks in Chapter 35 and CHAMPVA, ends routine re-examinations, and, if held for ten years before death, sets up DIC for a surviving spouse under §3.22 whether or not the death is service-related.
That last point reframes the whole exercise. Getting the rating right today is not just about this year’s income. Ten years of a total rating can be the difference between a surviving spouse receiving DIC for the rest of their life and receiving nothing at all.
The Advocate’s Take
When we fight for your rating, we are fighting for your family's finances too. One decision, filed correctly, can protect your spouse and children for a generation. One decision filed sloppily can leave them with nothing. Same veteran, same service, very different future.
Here is how the VA looks at it. At 30% and above, your monthly compensation increases for a spouse, children, and dependent parents, but only after you add them on VA Form 21-686c. Children between 18 and 23 stay on your award while in school, with VA Form 21-674. A Permanent and Total rating opens Chapter 35 education and CHAMPVA for your family. Ten continuous years at a total rating before death can secure DIC for your surviving spouse under 38 U.S.C. 1318. And since 2023, the old offset between the military Survivor Benefit Plan and DIC is gone, so surviving spouses no longer lose one to receive the other.
What I need from you: your marriage certificate, divorce decrees from prior marriages for you and your spouse, your children's birth certificates and Social Security numbers, school enrollment for any child 18 to 23, and your award letter showing your current rating and dependents.
Walk through it with me. We confirm the VA has every dependent listed. We add anyone missing and ask for back pay to the date you became eligible, when the law allows it. We check for P&T and request it if your conditions are stable. We map your 10-year date so your family knows exactly where they stand. Then we keep the file updated when a child turns 18, starts college, or leaves school.
The pitfalls: never adding a spouse after marriage, letting a student child drop off at 18, and missing the paperwork from a prior divorce. Shocking, I know, but a missing divorce decree can hold up a spouse's benefits for months.
Your part: gather your family documents and tell me every change in your household as it happens. We work WITH you, not FOR you. You built this family on your service. Let's make sure the VA pays to protect it.
Home loan fee waivers, dependent pay, and education benefits for your family all ride on your disability rating, and that rating was set at your claim exam. Watch the official VA videos below so you understand how the exam works, then make sure your rating is high enough to carry every family benefit you have earned.
Straight From the Source
The rating behind this benefit is set at your claim exam. Watch these official VA walkthroughs to understand what that exam involves and how to prepare.
The official overview of the VA claim exam process, what happens, who conducts it, and why it matters for your rating.
What the VA's own guidance covers, what to bring, how to report your symptoms honestly, and the mistakes that cost veterans rating levels.
Your Rating Ends the Day You Do. Your Paperwork Decides What Your Family Gets Next
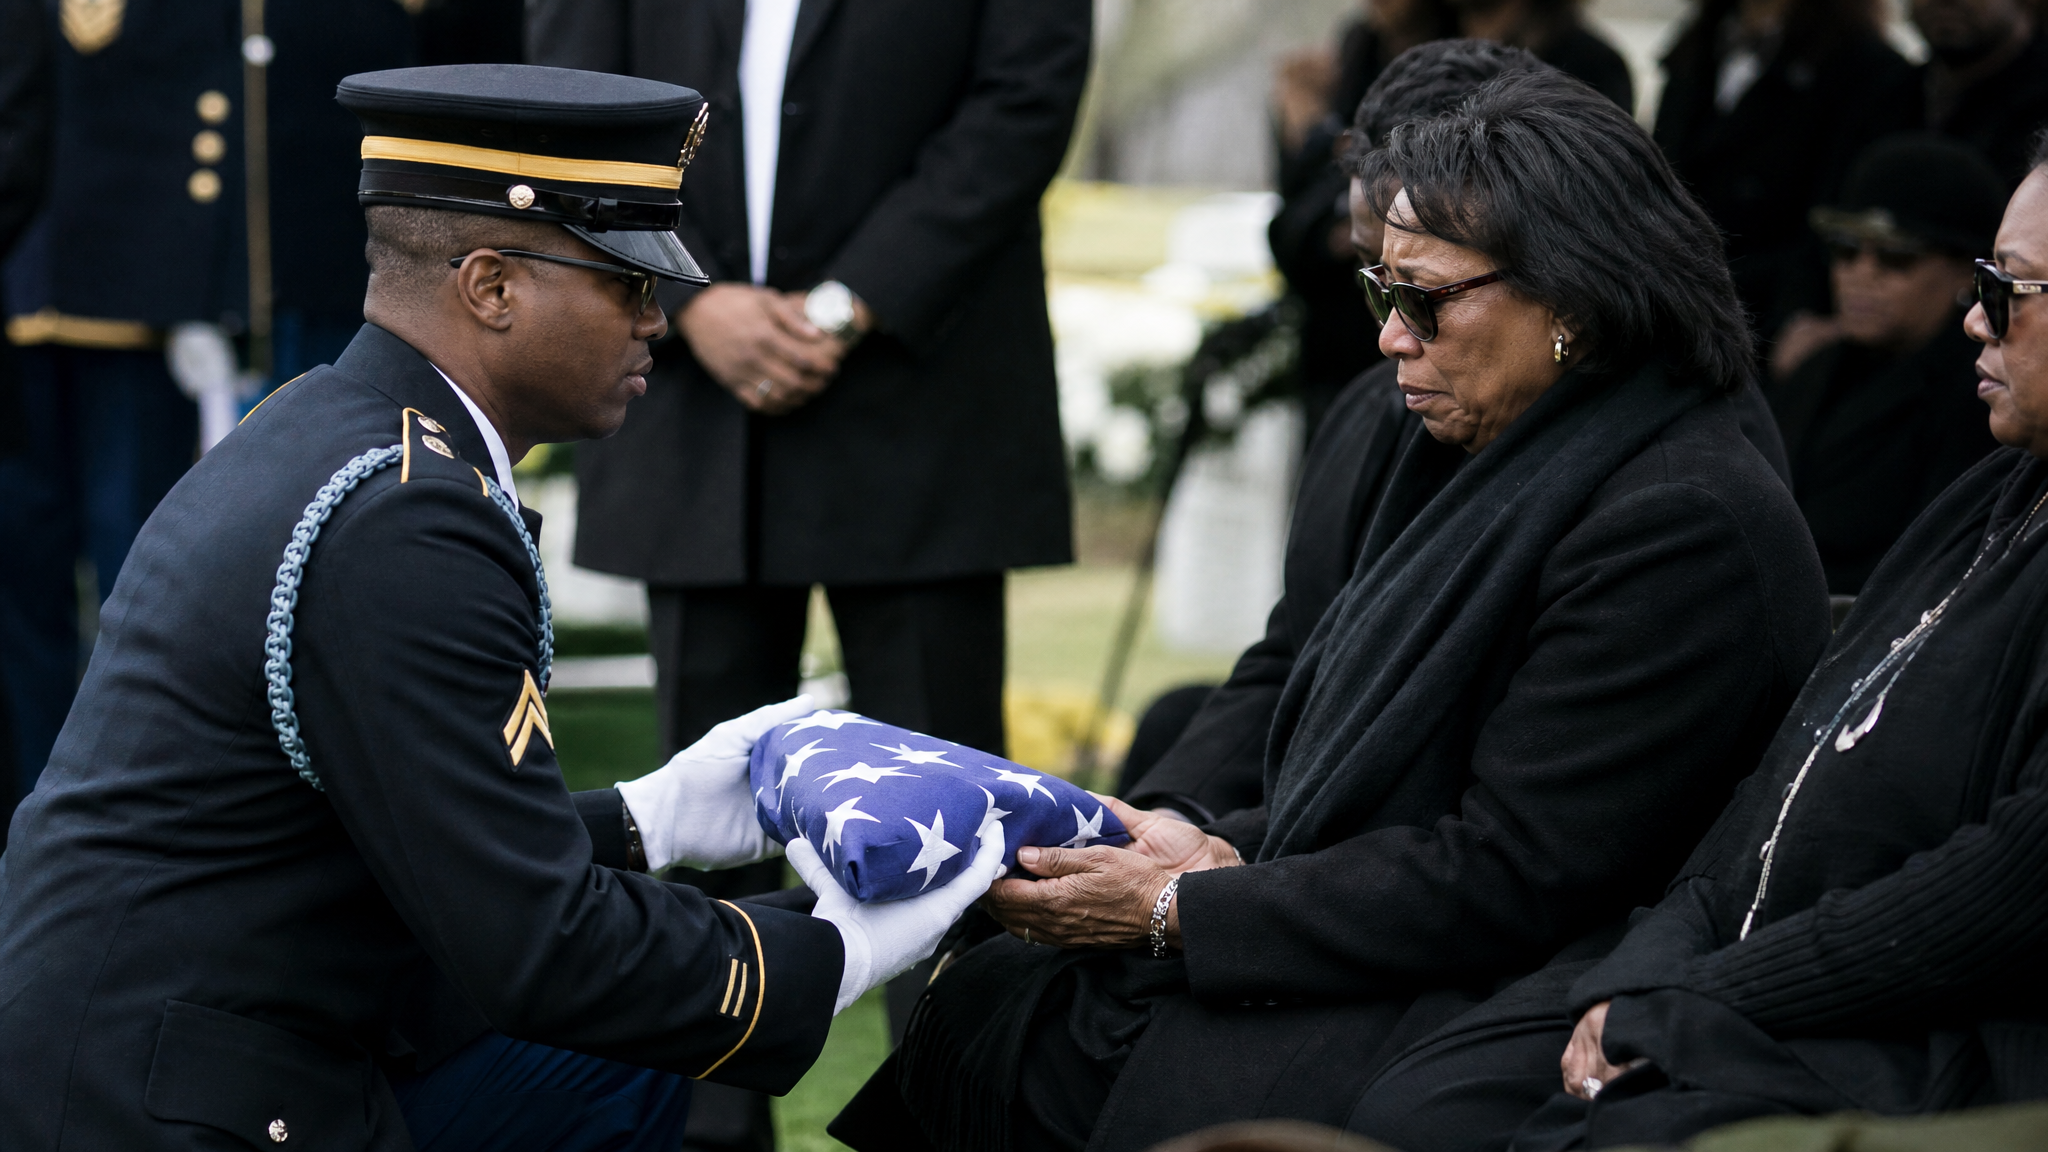
I have sat with too many widows holding a shoebox of papers and no idea where to start. Your compensation and pension stop at death, but your family's benefits do not have to. A surviving spouse can be owed DIC, survivors pension, burial benefits, accrued benefits, and the payment for the month you died. Every one of those depends on your family being able to prove who you were, what you were rated for, and who you were married to. That proof is paperwork you can put in order now, while you can still answer the questions.
Here is how the law treats that last month. Under 38 U.S.C. §5310 and 38 CFR §3.20, a surviving spouse is entitled to the compensation or pension you would have received for the month of your death, as if you had lived. If a claim for more was still pending, the difference is paid as an accrued benefit. That money belongs to your spouse. It is not a mistake the VA gets to quietly take back.
Here is the trap: families who assume a will settles everything. A will does not control your SGLI or VGLI payout, it does not let anyone manage your VA benefits if you can no longer do it yourself, and it does nothing if nobody can find your DD-214, your rating decision, or your marriage certificate. The documents that matter most for a veteran's family sit outside the will.
Your part: set aside one afternoon this month, gather the papers listed in the cards below, and tell one person you trust exactly where they are.
Four Pieces of Paper That Protect a Veteran Family, and the VA Rules Behind Them
Estate planning sounds like something for rich people. It is not. For a veteran, it is about making sure the benefits you fought for reach the people you meant them for, and that no stranger, court, or VA clerk gets to guess. I am not an estate attorney and I do not draft wills. What I can tell you is where VA rules collide with ordinary estate documents, because that collision is where families lose money.
Here is the trap: a durable power of attorney feels like it covers everything. For your bank and your house, it may. For your VA benefits, it does not. The VA runs its own fiduciary system, and a private power of attorney does not give anyone authority over your VA payments.
Your part: work through these four, and get a local estate attorney or a free legal-aid clinic to draft the documents themselves.
The Three Basics: Will, Durable Power of Attorney, Health Care Directive
Almost every plan starts with three documents. A will says who gets your belongings and who carries out your wishes. A durable power of attorney lets someone you trust handle money and paperwork if you cannot. A health care directive with a named health care proxy puts your medical wishes in writing and names who speaks for you. Give a copy of the directive to your VA primary care team so it is in your VA record when it matters. Many VA life insurance programs and community legal-aid clinics offer free or low-cost will preparation.
Your SGLI or VGLI Beneficiary Form Beats Your Will
Under 38 U.S.C. §1970(a), SGLI and VGLI pay the beneficiary named in writing on file before death. The Supreme Court held in Ridgway v. Ridgway that this federal designation controls over a state court order, and state laws that automatically drop an ex-spouse after divorce do not apply to it. If your form still names an ex-spouse, that person gets paid. The same is true for most bank, retirement, and commercial life insurance accounts. Review every beneficiary form after any marriage, divorce, birth, or death.
A Power of Attorney Does Not Run Your VA Benefits
If the VA decides under 38 CFR §3.353 that you cannot manage your own benefits, it appoints a fiduciary under 38 CFR Part 13, not whoever holds your power of attorney. You get written notice and the right to challenge the finding, and you can be represented by an accredited agent, attorney, or VSO in fiduciary matters. The VA prefers a fiduciary the beneficiary nominates, after a background check. Decide now who you would want, tell them, and put that wish in writing so your family can name them.
The Box Your Family Will Need on the Worst Day
Keep one fireproof box or folder with your DD-214, every rating decision and code sheet, your marriage certificate and any divorce decrees for you and your spouse, children's birth certificates, insurance policies, and your will. Those papers are what your survivors use to prove DIC eligibility, claim the month-of-death payment, file for accrued benefits within a year, and request burial benefits and honors. Tell your spouse or one trusted adult child where it is, and walk them through it once.
Your VA Check Belongs to You: Why Creditors Cannot Take It, and the Three Who Can
I talk to veterans every week who are scared of a collection letter. A credit card company, a medical bill, a judgment from an old car loan. They assume the collector can reach into the bank and take the disability check. In most cases, it cannot. Congress put that protection into the statute itself, and I want you to know exactly where it lives so nobody bluffs you out of your own money.
Under 38 U.S.C. §5301(a)(1), VA compensation, pension, and DIC cannot be assigned, are exempt from taxation, and are exempt from the claims of creditors, including attachment, levy, and seizure by any legal or equitable process, before or after you receive them. That last part matters. The protection does not vanish the moment the money hits your account.
There are three exceptions, and you should know all of them. First, the United States itself: if the VA says you were overpaid, it can withhold from your future payments to collect, which is why a waiver request matters so much. Second, the IRS can levy under §5301(d) for unpaid federal taxes. Third, child support and alimony under 42 U.S.C. §659 can reach the portion of your compensation that you receive in place of military retired pay you waived. A private credit card company, hospital, landlord, or collection agency is not on that list.
Here is the trap: the protection follows the money only as long as you can trace it. The Supreme Court held in Porter v. Aetna Casualty and Surety Co. that VA benefits sitting in a bank account stay protected while they keep the quality of money you can draw on for support. Mix them into an account full of wages, or turn them into stocks, land, or other permanent investments, and you can lose the protection. The statute also says property you buy with benefit money is not exempt from taxation.
Your part: pull your last rating or award letter and keep a copy with your bank records. If a creditor ever threatens you, that letter is how you prove where the money came from.
When a Creditor Freezes Your Account: The Bank Rule, and Four Ways to Keep the Money Safe
Knowing the law protects you is one thing. Getting your money released when the bank has already frozen the account is another. The Treasury Department wrote a rule for exactly this moment, and once you understand how it works, you can set up your banking so most freezes never touch you.
Here is the trap: the automatic bank protection only looks at federal benefits that arrived by direct deposit from the government. If your VA money came to you as a paper check you deposited, or was moved over from another account, the bank will not see it as protected, and you may have to go to court and prove the exemption yourself.
Your part: check how your VA payment reaches you today, and use these four cards to close the gaps before a creditor finds them.
The Two-Month Rule Your Bank Has to Follow
Under 31 CFR Part 212, when a bank receives a garnishment order it must review your account within two business days. It has to look back two months for federal benefits direct-deposited by the government, and it must leave you full access to the lesser of those deposits or your balance. You do not have to ask for this. The bank cannot charge a garnishment fee against the protected amount, and it must send you a notice within three business days. The rule does not apply when the order comes from the United States or from a state child-support agency.
Keep a Benefits-Only Account
The cleanest protection is a checking account that receives only your VA direct deposit and nothing else. No paychecks, no transfers in, no cash deposits. When everything in the account is traceable to the VA, the protection in §5301 is easy to prove and the bank's two-month review catches it automatically. Pay your bills from it if you like, just do not feed other money into it. If you already mix accounts, open a second one and change your direct deposit through VA.gov or your regional office.
Child Support and Alimony Are the Exception
42 U.S.C. §659 lets a court order for child support or alimony reach VA compensation only to the extent it is paid in place of military retired pay you waived to receive it. Compensation you would get with no retired pay in the picture is generally a different matter, and state courts still weigh your disability income when they set the amount. If you are a retiree going through a divorce or support case, have your family law attorney look at the waiver math before anything is signed.
Nobody Can Buy Your Future Payments
The same statute, §5301, bars any deal where someone pays you a lump sum now in exchange for the right to collect your compensation or pension later. Those offers are void, and they are a hallmark of pension poaching. A loan you repay voluntarily through payments you set up yourself is not barred, but read the terms and walk away from anyone who wants control of your VA deposit. If you need a plan, use a fee-only fiduciary financial planner who earns nothing from selling you products, or a free nonprofit credit counselor.
Where the VA Gets This Wrong
Failing to prompt for dependents when a rating crosses 30%, so the veteran misses the §3.401(b) one-year window; and never adjudicating permanence, which silently costs a family Chapter 35 and CHAMPVA.
Building a Finance & Family Benefits Claim That Wins
Every claim stands on three legs. Knock one out and the claim falls over, no matter how bad your symptoms are. Before you file, look at your file and find all three. If one is missing, that is the piece to build first. The VA will not build it for you, and filing without it usually just buys you a denial letter and lost time.
 01
A current diagnosis
A doctor has to say you have it, now, in writing. Not "reports symptoms of", a diagnosis. Without this leg, nothing else in the file matters.
 02
A link to your service
An event, an injury, an exposure, or an already service-connected condition. Service records, unit records, buddy statements, and your own account all count as evidence.
 03
A nexus that ties the two together
A medical opinion stating it is at least as likely as not that your service caused or aggravated the condition. That phrase is a legal standard: 50 percent or better. It is the leg most denials break.
Document the problem before you file
• Keep a dated symptom log for at least 30 days. Frequency, severity, and what it stopped you from doing.
• Get statements from people who see it, a spouse, a coworker, a battle buddy. Lay evidence is legal evidence.
• Pull your private treatment records. The VA only has to help; it does not have to go find everything.
• Write down what you have stopped doing. Lost work, lost sleep, lost activities. That is what impairment looks like on paper.
Your Rights in This Process
Most veterans walk into this system without knowing the rules the VA itself has to follow. That is how claims get denied for missing evidence the VA was supposed to help you find, and how exams get done by the wrong clinician. These six rights are written into federal regulation. Know them before you file, and make the VA honor every one of them when it decides your claim.
It costs nothing to file
Filing a VA claim is free. Accredited representatives may only charge for work on an appeal after an initial decision, and those fees are capped by 38 CFR §14.636.
The VA has a Duty to Assist you
Under 38 CFR §3.159 the VA must help you get the evidence it needs, and it must tell you what is missing before it denies you for missing it.
You can ask for a different examiner
You may request a trauma-informed clinician, or a clinician of a specific gender, for a C&P examination. Ask before the exam is scheduled.
You can claim every condition you have
There is no limit and no penalty. Primary conditions, secondary conditions, and conditions made worse by service all get filed.
You can appeal and be re-evaluated
A denial is not the end. You may submit new evidence, request a higher-level review, appeal to the Board, and ask for re-evaluation when your condition worsens.
You must be considered for TDIU
If your service-connected conditions keep you from holding substantially gainful employment, you may be paid at the 100 percent rate without a 100 percent rating.
When You Are Ready to File
Talk to an accredited representative before you file. It costs nothing to ask, and the order you file in changes what the VA is allowed to award you. Albert L. Thombs Jr. is VA-Accredited Claims Agent #45147. A short conversation now can save you a year spent waiting in the wrong review lane.
Your part starts at the kitchen table. Pull your DD-214, your rating decision if you have one, and the names of every doctor who treats you today. Under 38 CFR 3.159 the VA has to help you gather records, but it can only chase the records you tell it about. Leave a doctor off the 21-4142 and that treatment may never reach your file.
The application itself
This is the form that opens a disability compensation claim. List every condition you are claiming, and name the secondary conditions explicitly.
Release for private records
Authorises the VA to request records from your private doctors. Without it, treatment outside the VA may never reach your file.
Lay or buddy statement
The official form for your own statement and for statements from people who witnessed the event or the change in you.
What It Takes to Claim This Benefit
Confirm you meet the eligibility rules for this specific benefit, the criteria below and in the governing regulations tell you exactly what the VA is looking for.
Gather the proof that matches those rules, service records, medical evidence, income or dependency documents, and the physician statements the VA weighs.
File the right form the right way, the correct application, fully supported, so the VA cannot deny it on a technicality or delay it for missing evidence.
 Veteran Representation
 Veteran Representation
The Forms & Applications We File For You
These are the applications that drive this benefit. Start any of them on our site and an accredited agent prepares and files it for you, correctly, the first time.
DIC, Survivors Pension & Accrued Benefits
The survivor application for Dependency and Indemnity Compensation and related benefits.
Start this with usAid & Attendance / Housebound Exam
Documents a surviving spouse or parent who needs the regular help of another person.
Start this with usAppoint Us as Your Representative
Authorizes our accredited agent to act on your behalf with the VA on this benefit.
Start this with usSee How Ratings Drive This Benefit
Most benefits scale with your combined disability rating, and the VA does not add your ratings the way you would expect. Work the real math below. The VA uses the combined ratings table in 38 CFR 4.25, which applies each rating to whatever is left of your remaining efficiency, then rounds to the nearest 10. That is why a 50% and a 30% come out to 70%, not 80%. Before you assume you are short of a threshold for this benefit, run your own numbers here and compare them to your rating decision letter.
Why 50% + 30% Does NOT Equal 80%
The VA uses “whole-person” math, not simple addition. This is how ratings really stack.
The VA always begins from a whole, healthy person (100%).
50% of 100 is subtracted. You have 50% “efficiency” left.
30% is taken from the REMAINING 50 (0.30 × 50 = 15). 50 − 15 = 35 left.
100 − 35 = 65, then rounded to the nearest 10 → 70%.
Bottom line: 50% and 30% combine to 65% → rounded to 70%, not 80%. The same math turns two 50% ratings into 75% → rounded to 80%, not 100%. Every rating you add is worth less than the last. That is why which conditions you claim, and in what order, matters as much as how many.
 Veteran Representation
Not sure if you qualify?
An accredited agent reviews your eligibility for this benefit at no cost and tells you straight whether it is worth pursuing. If it is, we prepare and file every form for you.
Keep Reading
One page never tells the whole story of a claim. The VA rates every condition on its own evidence, its own exam and its own diagnostic code, and the pieces connect in ways most veterans never see until a decision letter lands. These are the pages that pick up where this one stops. Read them before you file, not after a denial, because the cheapest fix in this process is the mistake you never make.